Skipping the Latte Won't Buy the House: The Finance Advice That Got the Scale Backwards
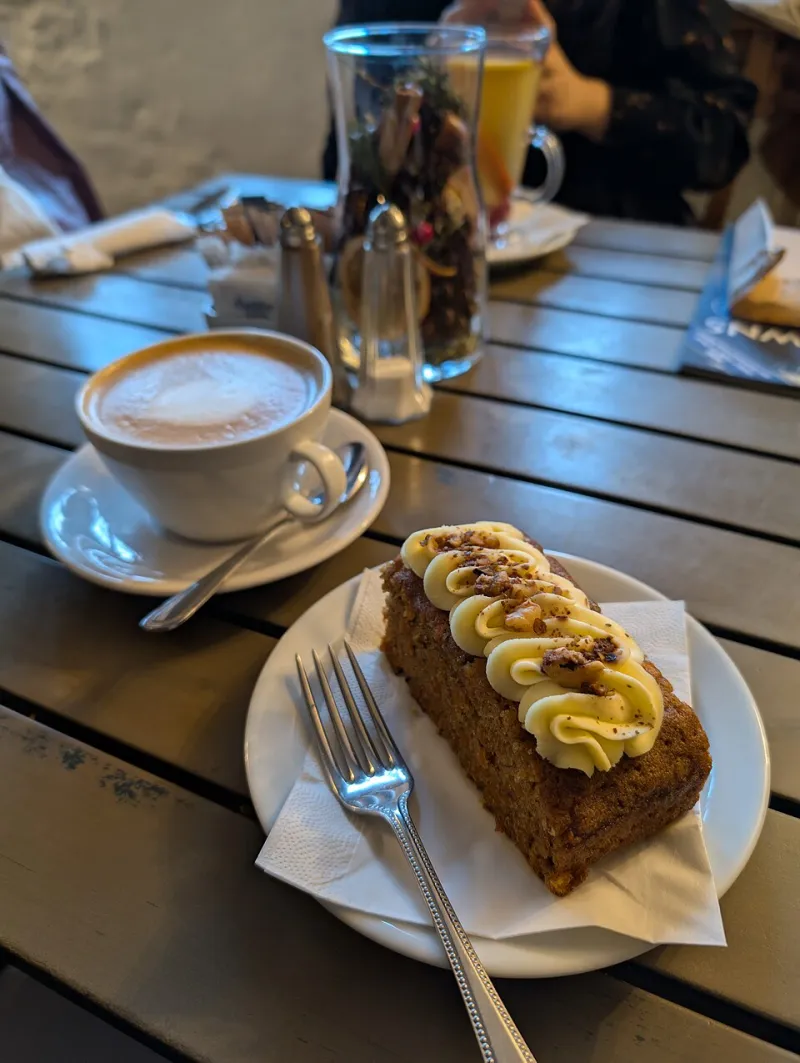
Photo: Andy Li, CC0, via Wikimedia Commons
You have probably heard the pitch. Five dollars a day on coffee, invested instead at 7 percent, becomes a few hundred thousand dollars over a working lifetime. Cut the small stuff, the logic goes, and the big things take care of themselves.
The arithmetic checks out. The conclusion doesn't. And the gap between the two is one of the more revealing stories in American personal finance.
Where the idea came from
The phrase "the latte factor" was popularized by financial author David Bach, who introduced it in a 1999 book and expanded it in The Automatic Millionaire in 2005. It became a fixture of morning television and workplace retirement seminars.
Here's the thing that gets lost: the original argument was mostly about automation, not deprivation. Bach's point was that habitual small spending is invisible — nobody decides to spend $150 a month on coffee, it just happens — and that automatically routing money into a 401(k) beats relying on willpower. That's good advice. It's also the part that quietly fell out of the retelling.
What survived was the sermon: your financial problems are hiding in your beverage.
The math, honestly
$5 a day is about $1,825 a year. Invested at a 7 percent average annual return for 40 years, that's roughly $360,000. Most people wouldn't call that nothing, and they'd be right. Compounding is genuinely one of the few near-magical things in personal finance.
Now put it next to the other column of a typical household budget.
The median US home price sits above $400,000, and the monthly payment on it is the single biggest line item most families will ever carry. Annual childcare for one infant runs somewhere between $11,000 and $16,000 depending on the state, and in many metro areas it costs more than in-state college tuition. A family health insurance premium through an employer now averages around $25,000 a year, with the employee picking up thousands of that. Owning and operating a car costs roughly $12,000 a year by AAA's estimate. Add rent or a mortgage on top of all that.
Against a median household income in the low $80,000s, coffee is a rounding error. It's maybe 2 percent of the budget. Housing, transportation, healthcare, and childcare together can easily consume 60 to 70 percent.
So yes: $360,000 from coffee over forty years is real money. It's also roughly the cost of one house, arriving four decades from now, purchased with forty years of decisions you'd have to make perfectly, in a market where the house will have appreciated the entire time. You cannot skip your way to a down payment. You can, however, cut the coffee and still be priced out of the neighborhood.
Why we keep hearing it anyway
Because the advice is emotionally perfect and structurally useless, and that combination sells.
It's actionable. You cannot personally rewrite zoning laws, negotiate your employer's insurance contribution, or fix the cost of childcare. You can skip a latte tomorrow morning. Advice that offers a doable action feels like help, even when the action is too small to change the outcome.
It's also flattering. Framing a systemic cost problem as a discipline problem makes the reader the protagonist. And it lets whoever is giving the advice feel useful without ever touching the uncomfortable numbers.
Finally, there's a real kernel underneath. Subscription creep is genuinely a thing. The average household now pays for a rotating stack of streaming services, apps, and memberships that quietly add up to hundreds a month. Automating savings still works better than trying harder. If the latte factor were presented as "audit your recurring charges and set up an automatic transfer," it would be unglamorous but accurate.
What the numbers actually suggest
The biggest financial lever most households have is not the coffee. It's the top three line items and the size of the paycheck feeding them.
Start there. A 10 percent raise or a better job offer outranks decades of skipped lattes. Refinancing, renegotiating a car payment, switching insurance, or moving to a cheaper school district can move four figures a month. Childcare and housing costs respond to decisions made once, not daily.
Then do the boring behavioral stuff anyway, because it works: automate the 401(k) contribution, let it rise with each raise, and don't touch it.
And buy the coffee if you like the coffee. The drink was never the problem.